Buying Your First Home in Billings, MT: 2026 Programs and Grants
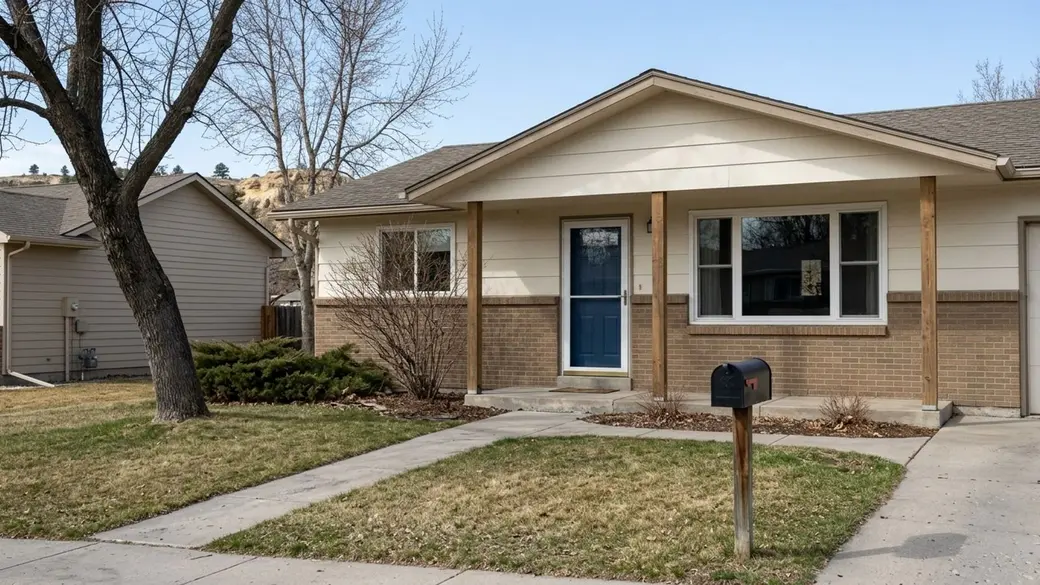
For anyone buying a home in Billings, MT, the median home sale price sits at around $389,642 right now. That's lower than a lot of national averages, but saving for a down payment still takes real time - especially if you're doing it on a single income or without family help.
The good news is that both Montana and the City of Billings have programs built specifically to reduce what you need at closing. If you're buying in Yellowstone County, you may have access to deferred loans, tax credits, and below-market interest rates that can make a genuine difference.
State and Local Home Buyer Programs Available in Billings
There are several layers of assistance available to first-time buyers in Billings, MT, and they stack in ways that aren't always obvious. The Montana Board of Housing (MBOH), a division of the state Department of Commerce, runs the primary statewide programs and works through participating local lenders - not directly with buyers.
MBOH offers affordable fixed-rate mortgages through those lenders. You can use the MH Regular Bond Program for a standard 30-year fixed-rate mortgage, or the MH 80% Combined Program, which covers 80% of the purchase with a primary loan and finances the remaining 20% with a second loan.
State-Level Options for Montanans
Qualified veterans buying their first home can use the Montana Veterans' Home Loan Program. There's also a Mortgage Credit Certificate (MCC) through Montana Housing, which converts a portion of your annual mortgage interest into a direct tax credit - worth understanding even if it sounds complicated at first.
City and County Assistance
The City of Billings First Time Home Buyer Program offers up to $15,000 in assistance to low-income households. It comes as a zero-interest, deferred-payment loan - no monthly payments, but it must be repaid in full if you sell, refinance, or move out of the house. Think of it as a loan that stays quiet as long as you stay put.
Regional Non-Profits and Federal Loans
NeighborWorks Montana approves HOME fund assistance in Yellowstone County, though availability within incorporated city limits varies. The Federal Home Loan Bank's Home$tart program provides up to $7,500 to eligible borrowers, scaling up to $15,000 under Home$tart Plus for buyers currently receiving public housing assistance. FHA, VA, and USDA loans remain popular options for buyers who need flexible underwriting standards.
Down Payment Assistance and Grants in Yellowstone County
A lot of buyers walk in assuming they need 20% down. They don't - and local assistance can cover a significant portion of what they do need. Before you apply for anything, though, it helps to know what you're getting.
Neither of the main Montana Housing down payment assistance options is technically a grant. Both are second loans that you'll eventually repay. The terms are subsidized to keep monthly costs manageable, but the money doesn't disappear.
State Down Payment Assistance Amounts
The Bond Advantage Down Payment Assistance program provides a second loan for up to 5% of the home's sales price, capped at $15,000. You can apply those funds toward your down payment or closing costs. The MBOH Plus 0% Deferred Down Payment Assistance Program is a separate option - a 0% interest second mortgage for up to 5% of the sales price, with a maximum of $6,500 from a single source.
Local Deferred Loans
The City of Billings program works the same way: a deferred loan, not a grant. The $15,000 is secured with a Promissory Note, Deed Restriction, and Trust Indenture. Because it's non-forgivable, factor that repayment into your long-term math if you think you might sell within the next several years.
Low and Zero Down Payment Options
If a second mortgage isn't what you want, federal programs offer another path. VA loans and USDA loans allow for 0% down for eligible military members and rural property buyers, respectively. FHA loans require just 3.5% down - a common route when state assistance funds aren't available.
Eligibility Rules for First-Time Buyers
Eligibility comes down to three things: household income, household size, and credit history. Each program sets its own thresholds, and underwriters will verify those numbers against your tax returns and pay stubs - so accuracy matters from the start.
For the City of Billings First Time Home Buyer Program, annual household income limits range from $41,400 to $104,050 depending on how many people live in the home. State programs run on a slightly different scale.
State Income Limits
To qualify for Bond Advantage down payment assistance, basic Montana Housing income limits apply. Right now that's $80,000 for one- to two-person households and $90,000 for households with three or more people - though those figures can shift depending on the specific location and program.
Credit Score Minimums
Bond Advantage requires a Montana Housing 30-year first mortgage and a credit score of at least 620. The City of Billings program also requires a mid-credit score of at least 620. Applicants with no credit history might still qualify if their loan meets the underwriting standards of the primary mortgage guarantor.
Homebuyer Education Requirements
Standard FHA loans accept credit scores down to 580 with a 3.5% down payment, but state programs are more restrictive. Montana Housing requires applicants to complete a Homebuyer Education course if their credit score is under 680, their front-end debt ratio exceeds 31%, or their back-end debt-to-income ratio is above 41%.
Budgeting for a Home Purchase in Billings
Local market conditions determine how far your approval gets you. Recent data shows 671 homes in active inventory across Billings, MT, with an average of 61 days on the market.
With a median sale price of roughly $389,642 and 3.9 months of supply, this is a relatively balanced market. You'll have some breathing room to view homes and negotiate - which wasn't always the case.
The 3-3-3 Rule for Home Buying
Financial advisors often point to the 3-3-3 rule as a starting framework: price a home at no more than three times your annual gross income, save 20% for a down payment to avoid mortgage insurance, and keep your monthly housing payment under 30% of your gross monthly income. Strict adherence is difficult for most first-time buyers, but it's a useful ceiling when you're setting a maximum budget.
Income Needed for Local Prices
Buyers earning closer to $50,000 should focus on townhomes or smaller single-family homes in the $200,000 range to keep debt-to-income ratios in acceptable territory. To comfortably afford a $400,000 house in Billings, a household typically needs an annual income exceeding $95,000, assuming current interest rates and a modest down payment.
Down Payments and Purchasing Power
The cash you bring to closing affects your monthly payment, your interest rate, and which loan products you can even access. Small differences in down payment amount have a larger ripple effect than most buyers expect.
It's worth sitting down with your savings number and working through what it gets you in Yellowstone County before you start touring homes.
Minimum Cash for a $300,000 House
Either way, you'll also need to cover closing costs - budget an additional 2% to 5% of the purchase price, which adds $6,000 to $15,000 to your total cash requirement. On a $300,000 home with an FHA loan, the 3.5% minimum down payment is $10,500. A conventional loan at 3% down brings that to $9,000.
Stretching a $10,000 Down Payment
A buyer with exactly $10,000 saved for a down payment has a maximum purchase price of roughly $285,000 using an FHA loan, assuming closing costs are covered separately. Pair that $10,000 with a Montana Housing assistance loan, and the same buyer can cover both the down payment and closing costs on a higher-priced property without clearing out their savings entirely.
Participating Lenders and Tax Incentives
State and local programs don't originate loans directly - you work with an approved private lender who then accesses Montana Board of Housing funds on your behalf. The Montana Commerce Department keeps a regularly updated list of participating lenders, and working with a loan officer who already knows these programs cuts down on delays considerably.
Approved Lenders Serving Billings
Several local and national institutions have branches in Billings and participate in MBOH programs: First Interstate Bank, Guaranteed Rate, Guild Mortgage, Opportunity Bank, Premier Mortgage Resources, Stockman Bank, Synergy One Lending, US Bank, Western Security Bank, and Yellowstone Bank.
Mortgage Credit Certificates
The Mortgage Credit Certificate (MCC) is separate from the loan programs and worth knowing about. It gives first-time buyers a direct tax credit equal to 20% of annual mortgage interest paid, up to $2,000 per year. There's an initial $500 application fee to Montana Housing and a potential $250 fee from the lender, but the credit repeats every year for the life of the loan - so the math tends to work in your favor over time.
Steps to Buy Your First Home in Montana
Get your finances in order before you start walking through houses. Sellers expect a pre-approval letter with any offer, and showing up without one puts you at a real disadvantage.
The timeline from application to closing generally runs 30 to 45 days - assuming your documentation is complete and accurate from the beginning. Gaps in paperwork are the most common reason closings slip.
Application Checklist
Lenders will ask for two years of federal tax returns, two years of W-2s, and your most recent 30 days of pay stubs. You'll also need two months of bank statements to document your down payment and closing cost funds. If you're self-employed, prepare to provide profit and loss statements as well.
Connecting with a Local Professional
Start by contacting one of the participating MBOH lenders in Yellowstone County to check your credit and set a realistic budget. Once you have a pre-approval letter spelling out your maximum purchase price and which assistance programs you qualify for, you can work with a real estate agent to find homes that fit within that range.
Frequently Asked Questions
Does Montana have a first-time home buyer program and how do you qualify in Billings?
Yes. Montana offers several programs through the Montana Board of Housing, including the MH Regular Bond Program and down payment assistance loans. To qualify, you need a minimum credit score of 620, must meet income limits of $80,000 to $90,000 depending on household size, and must work with an approved participating lender.
What is the first-time home buyer grant in Billings, Montana and how much is it?
The City of Billings First Time Home Buyer Program offers up to $15,000 in assistance. It's a zero-interest, deferred-payment loan rather than a true grant - meaning it must be repaid in full if you sell, refinance, or move. The state also offers up to $15,000 through its Bond Advantage program.
What disqualifies you as a first-time home buyer in Montana?
You'll be disqualified if your household income exceeds the program limits, which range from $41,400 to $104,050 for the City of Billings program. A credit score below 620 will also disqualify you from Montana Housing programs, as will purchasing an investment property instead of a primary residence.
What's the minimum down payment for a $300,000 house in Billings?
The minimum down payment is $10,500 if you use an FHA loan, which requires 3.5% down. Conventional loans can require as little as 3%, or $9,000, while VA and USDA loans allow eligible buyers to purchase with zero money down.
What salary do you need to afford a $300K–$400K house in Billings, MT?
To afford a $400,000 house, a buyer typically needs an annual salary of at least $95,000 to keep their debt-to-income ratio manageable. A $300,000 house usually requires a salary closer to $70,000, depending on current interest rates and the size of your down payment.
What is the step-by-step process to apply for a first-time buyer loan in Billings?
Start by gathering your financial documents - two years of tax returns and recent pay stubs. Then contact an approved Montana Board of Housing lender like First Interstate Bank or Stockman Bank to get pre-approved and check your eligibility for assistance programs. If your credit score is under 680 or your debt ratios are high, you'll also need to complete a required Homebuyer Education course.
Categories
Recent Posts